While the proposed Late Payment Regulation is motivated by the commendable goal of supporting and protecting small and medium-sized enterprises (SMEs) in the area of payments, as currently drafted, it captures transactions where both parties are large companies and potentially prevents SMEs and large companies alike using supply chain financing. As the co-legislators consider the proposal, they should create an exemption for transactions between large businesses which do not require the same protections as SMEs and benefit from additional flexibility, as well as clarify the regulation’s impact on supply chain financing. Access our position below to learn more.
Position on the Late Payment Regulation
Related items
News
9 Sep 2026
Advancing EU-US consumer protection cooperation
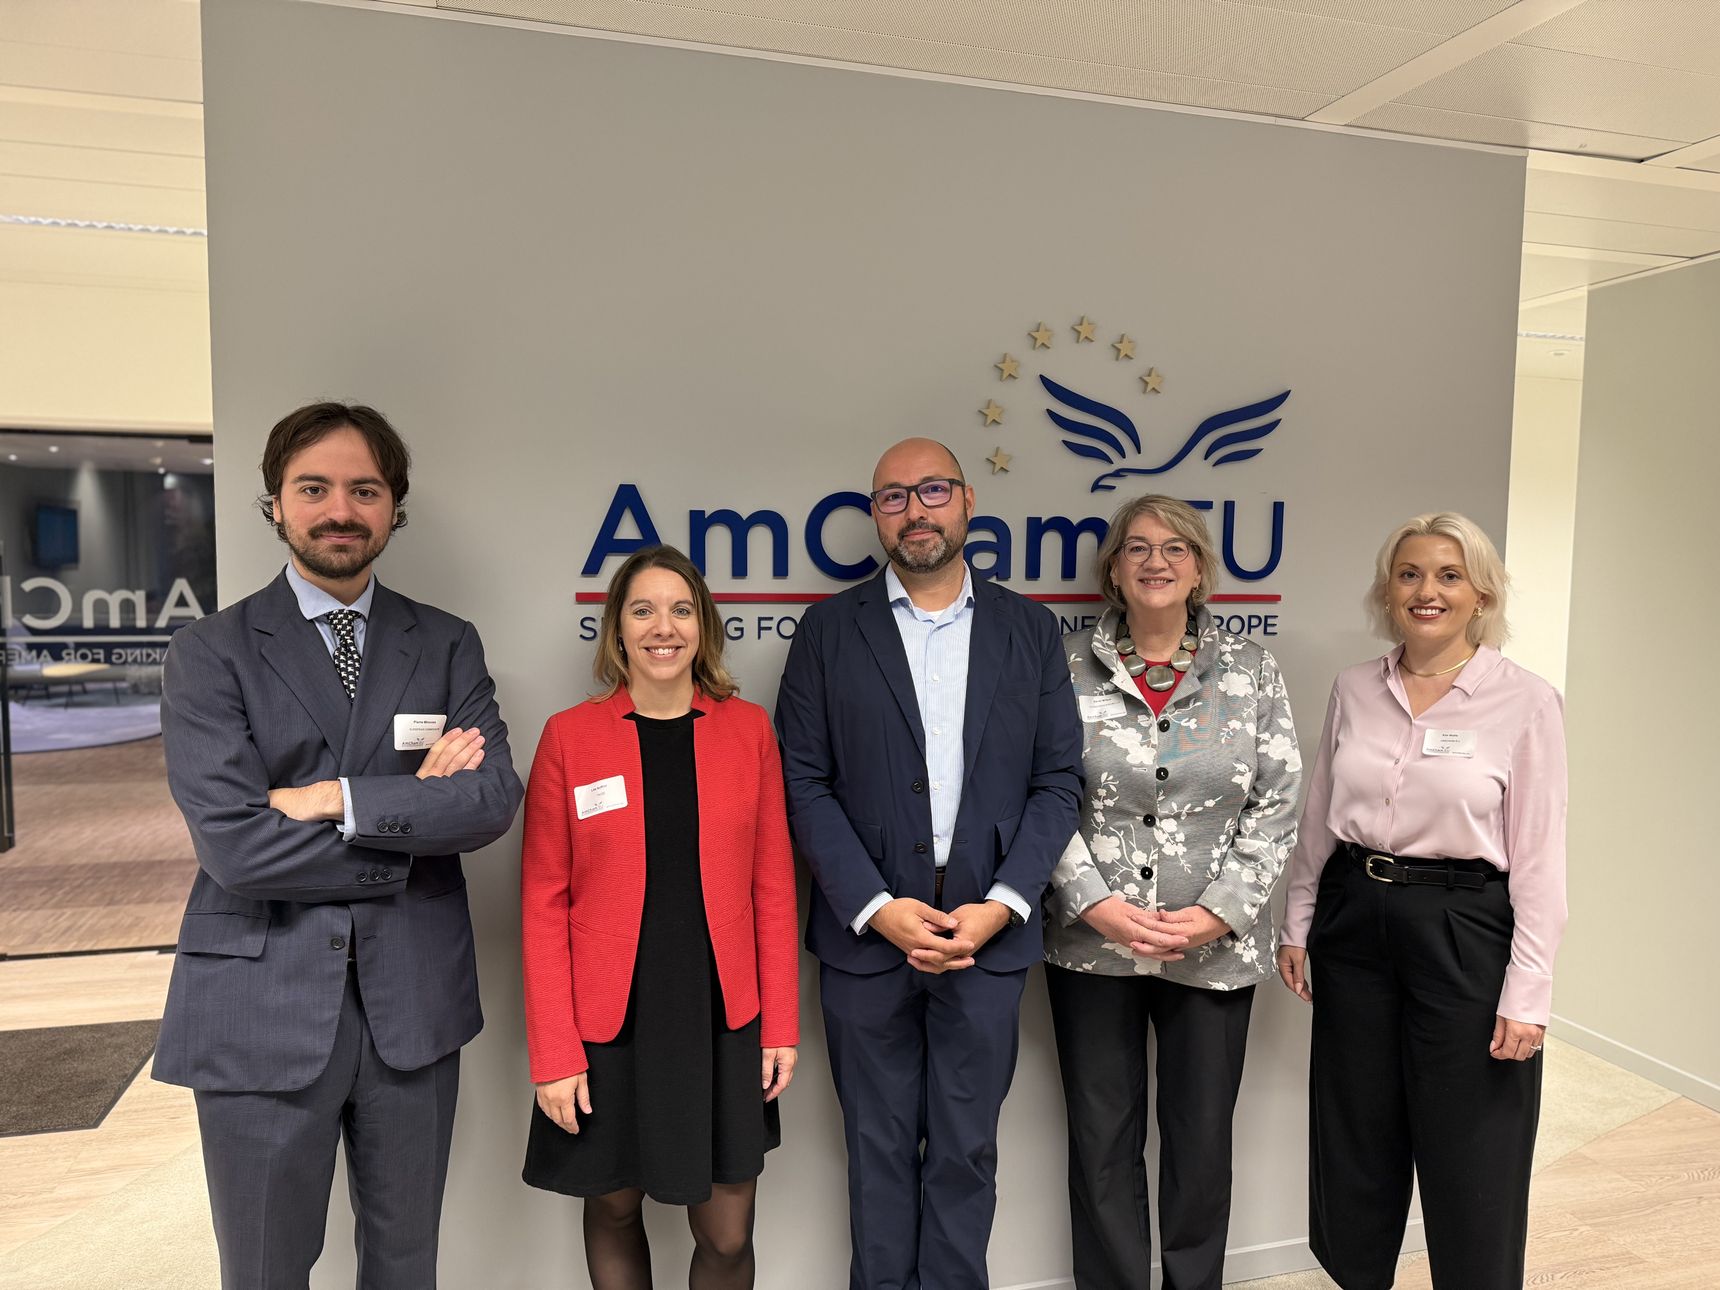
On Wednesday, 9 September, AmCham EU hosted a roundtable on transatlantic consumer cooperation as a part of the European Union’s International Product Safety Week and the International Consumer Product Health and Safety Organization’s International Symposium. The discussion explored how closer EU-US cooperation could improve consumer outcomes in practice, from product safety and recalls to fair commercial practices, as the European Commission prepares to revise the Consumer Protection Cooperation framework.
The exchange began with reflections on the state of play of transatlantic consumer cooperation from Sarah Wilson, Partner and Chair of the Product Safety Practice Group, Covington; Pierre Minoves, Acting Policy Assistant, Cabinet of Commissioner McGrath, European Commission; and Léa Auffret, Director, Transatlantic Consumer Dialogue. This was followed by a discussion with leading EU and US experts, officials and AmCham EU member representatives about how improving EU-US cooperation in consumer protection can deliver benefits for businesses, consumers and regulators. Thank you to Covington for sponsoring and to Razvan Antemir (Amazon), Chair, Consumer Affairs Committee, AmCham EU for moderating.

Position Paper
8 Sep 2026
Digitising product information across the Single Market
Together with 21 other associations, AmCham EU is calling on EU policymakers to modernise product information requirements and allow regulatory information to be delivered digitally, as a complement or alternative to physical documentation. Paper-based obligations and fragmented language requirements complicate supply chains and generate unnecessary waste. Digital delivery can make information more accessible and available in consumers’ preferred languages, while supporting the EU’s simplification goals. As the Commission revises the New Legislative Framework, policymakers should establish a clear legal basis for digital product information across sectors, while preserving flexibility where physical information remains necessary across the EU. Learn more in the joint statement.

News
22 Jul 2026
Banking Competitiveness Report: Single Market integration and openness must drive reform
The European Commission’s Banking Competitiveness Report comes at a critical moment for Europe’s investment agenda. Closing Europe’s investment gap requires a banking sector able to mobilise capital at the scale the Savings and Investments Union demands. This is dependent on a Single Market that is not only competitive and integrated but open for all banks operating in the EU to act as facilitators of investment. The report provides a window of opportunity to anchor that openness at the centre of the competitiveness agenda.
The report correctly identifies a set of barriers holding back Europe’s banking competitiveness, both in the regulatory framework and in the way that framework is supervised. Undue complexity and divergent national implementation continue to raise the cost of financing for European households and businesses, underlining the need for an ambitious banking omnibus that simplifies rules and delivers greater consistency across the EU. At the same time, the report is right to call for a more proportionate, risk-focused supervisory culture that examines whether burdensome practices are weakening the attractiveness of Europe’s banking ecosystem. A new banking competitiveness agenda should build on both priorities: simpler, more coherent rules and supervision that enables internationally active banks to support investment.
Internationally active banks, including third-country groups with a substantial European footprint, are central to delivering this agenda. These institutions channel global capital to European companies, underpin the liquidity and depth of EU capital markets and help international investors finance opportunities in Europe. Europe remains a strategic market for these firms, and their investment demonstrates confidence in European growth, European companies and European opportunity.
The test of genuine integration is whether a banking group can serve customers across the Single Market without rebuilding its operations in each Member State. The report recognises that divergent national application of EU rules discourages banks from offering pan-European services and consequently results in costly duplication and regulatory burden across jurisdictions. A more competitive framework would enable European and international institutions to thrive in Europe, offering clients choice and a full suite of payment and banking services across the Single Market.
Coherent implementation will determine whether these reforms enhance competitiveness. Where the framework adapts international standards to EU specificities, the test should be whether the result preserves a level playing field for banks competing in global markets and remains consistent with the standards those banks apply across jurisdictions.
Policy priorities
Insights and advocacy driving Europe’s policy agenda. Our priorities support growth, innovation and a stronger transatlantic economy.
Membership
Connecting business and policymakers to strengthen the voice of American companies in Europe.