On Wednesday, 18 July, AmCham EU visited Budapest, Hungary to discuss our priorities for ongoing and upcoming tax files. During several meetings, delegates and officials discussed ways that tax policy can contribute to the top priority of the Hungarian Presidency of the Council of the European Union: Europe’s competitiveness. The delegates gained insights into how the Hungarian government works on domestic issues and EU policy. Learn how Hungary can maximise their presidency in our recommendations.
Taking note of tax policy in Budapest

Related items
Position Paper
28 Oct 2026
Industry calls for ambitious tax simplification
AmCham EU has joined 22 other business, financial and professional associations in calling on Member States to reach agreement on the Commission’s Tax Simplification Package. The measures could save businesses operating in Europe around €8 billion a year, money currently absorbed by complexity rather than invested in growth. Tax collected only to be refunded and withholding taxes that hinder investment in the Single Market add costs without strengthening the tax base. Europe has already strengthened its tax framework, so simplification can go ahead without weakening enforcement. Agreement will only matter if the ambition of the package survives the negotiations. Read the full joint statement here.
News
19 Oct 2026
Heading to Vilnius ahead of the upcoming Lithuanian Presidency
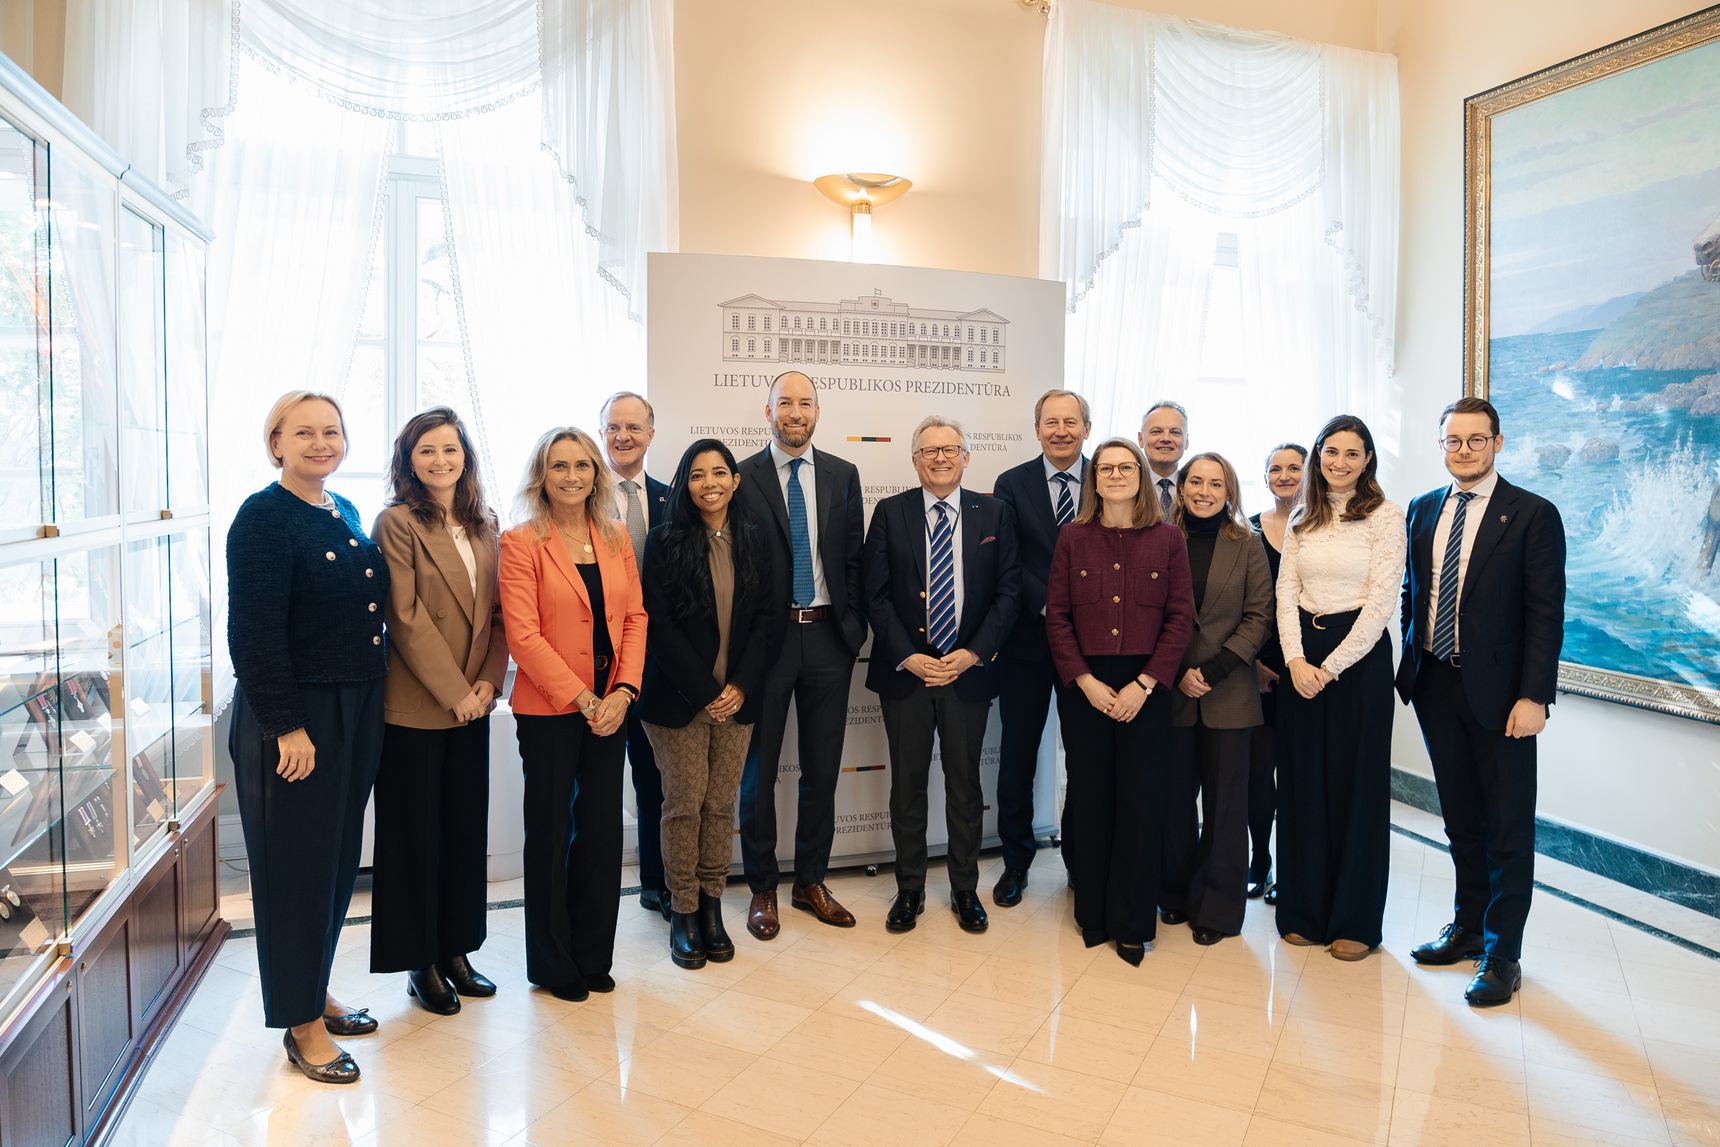
From Wednesday, 14 October to Friday, 16 October, AmCham EU visited Vilnius, Lithuania ahead of Lithuania’s upcoming Presidency of the Council of the European Union. The delegation met with Lithuanian policymakers and business representatives to exchange views on EU policy priorities, Europe’s competitiveness and the transatlantic partnership. The visit forms part of AmCham EU’s ongoing engagement with Member States ahead of their Presidency.

Position Paper
25 Sep 2026
Closing the gap between customs and VAT rules
The reform of the Union Customs Code changes who is treated as the ‘importer’ when a non-EU company uses an indirect customs representative. That creates a problem under the EU VAT Directive, which links import VAT deduction to being identified as the importer or consignee. In practice, the non-EU company may no longer meet that requirement, while the customs representative may not qualify for the deduction either.
That could leave import VAT irrecoverable and create uncertainty for businesses using established import models. The Commission should ensure that the non-EU principal can still be identified in customs data for VAT purposes and fix the mismatch between the UCC and the VAT Directive.
Learn more about what changes are needed to keep import VAT deductibility workable under the new customs framework.
Policy priorities
Insights and advocacy driving Europe’s policy agenda. Our priorities support growth, innovation and a stronger transatlantic economy.
Membership
Connecting business and policymakers to strengthen the voice of American companies in Europe.