Tax policy may not always make headlines – but its benefits certainly are
The Taxation Omnibus and the recast of the Directive on Administrative Cooperation (DAC) are unlikely to dominate headlines.
Terms such as withholding tax, administrative cooperation and cross-border reporting do not immediately bring to mind the questions that matter most to the Brussels crowd: How will the EU become more competitive? How can we facilitate scale and innovation? Will businesses invest here rather than elsewhere?
But these questions are more closely connected than they might appear.
Tax rules influence where businesses invest, how quickly they can grow and how much of their resources can be devoted to innovation, hiring and productive activity. A well-designed tax system can help create the conditions for economic growth. A fragmented, unpredictable or unnecessarily burdensome one can quietly work in the opposite direction.
That is why the European Commission’s recently proposed Taxation Omnibus and DAC recast matter. The package seeks to modernise the EU’s direct tax framework, eliminate unnecessary requirements and make it easier for businesses to operate across borders, while preserving safeguards against tax fraud, avoidance and evasion. The Commission estimates that the proposals could reduce compliance and financial costs for businesses by approximately €7.9 billion.
This is an excellent example of pro-growth tax policymaking. But it prompts a wider question: what would happen if all EU tax legislation were designed with growth and competitiveness in mind from the outset?
Europe needs growth – and tax policy has a role to play
Europe’s economic challenges are well documented. Productivity growth has slowed, energy costs have risen and global competition has intensified. At the same time, the EU needs unprecedented levels of investment to support innovation, strengthen its security and resilience, develop new technologies and deliver the green and digital transitions.
EU tax policy cannot solve all these challenges. However, it can ensure that governments can raise the revenues needed to fund public spending, while companies have the lowest barriers and highest incentives needed to contribute.
Right now, one of the biggest issues with EU tax policy is that EU tax rules are either highly duplicative or implemented inconsistently. Every euro and every hour spent navigating these inefficiencies distracts limited resources from high-value work for both companies and tax authorities.
Companies cannot invest these resources in R&D or other growth opportunities. While administrative burdens related to tax policy may not stop a company from making an investment, it may factor into broader hesitations or impact decisions about financing, production, business structures and the location of investment.
Tax authorities, similarly, cannot spend their time on high-value activities like tackling tax avoidance. This limits the effectiveness of key rules like the Anti-Tax Avoidance Directive and the administrative cooperation rules on anti-tax avoidance information (DAC 6), as tax authorities spend more time weeding through non-comparable or duplicative information.
In some cases, divergent implementation can even undermine the Single Market. This was the case in the Interest & Royalties Directive and Parent Subsidiary Directive, where the co-legislators agreed to support the Single Market by getting rid of intra-EU withholding tax on routine inter-group transactions. Even so, the implementation of these two directives was so challenging that companies often declined to pursue these exemptions.
Pro-growth tax policy, in the EU context, does not mean weakening tax rules. Instead, it means optimising the effectiveness of the legislation we have at hand.
This cost includes more than the amount paid in tax. It also includes economic distortions, administrative expenditure, compliance costs, legal uncertainty and the cross-border friction created when supposedly common European rules produce multiple national systems in practice.
Good tax policymaking is a lifecycle
Good tax policymaking takes place over the entire lifecycle of a file, from inception to revision. The Taxation Omnibus and DAC recast are helpful because they recognise that tax rules need evidence-based maintenance.
The DAC has evolved through successive amendments as the EU has expanded administrative cooperation and the exchange of information between tax authorities. The recast now seeks to consolidate and improve that framework. Similarly, the Taxation Omnibus examined the role of existing anti-tax avoidance rules in view of international policy developments to identify overlaps, outdated provisions and barriers to cross-border activity.
But simplification should not only happen after complexity has accumulated.
The EU should apply pro-growth discipline throughout the lifecycle of every tax file: when deciding whether action is needed, when designing the legislation, during negotiations, when implementing it nationally and after businesses and authorities have gained practical experience with the rules.
This is the central argument of AmCham EU’s new paper on pro-growth tax policymaking.
Drawing on the experience of companies operating across every EU Member State and around the world, the paper proposes five principles for designing, implementing and evaluating EU tax policy:
Economic efficiency
Discipline across the full tax policy cycle
Evidence-based accountability
Strong Single Market
Neutrality and fair competitive conditions
Together, these principles provide a practical test for new and existing tax measures. Is the proposal based on a clearly defined problem? Have less distortive alternatives been considered? Are compliance and administrative costs treated as part of the policy design? Can the rules be implemented consistently across 27 Member States? Will equivalent businesses and transactions receive equivalent treatment? And is there a credible mechanism for revisiting the measure when experience shows that its assumptions were wrong?
These questions may sound technical. Their consequences are anything but.
Simplification is a means to an end
The Taxation Omnibus and DAC recast are promising examples of how tax policy can support competitiveness without weakening legitimate enforcement objectives. They show that it is possible to preserve strong protections while reconsidering requirements that are duplicative, outdated or unnecessarily costly.
The Commission should now carry that approach into the rest of the EU’s fiscal agenda.
Europe should not wait for tax rules to become unmanageable before simplifying them. New proposals should be designed for administrability from the outset. Their likely effects on investment, innovation and the Single Market should be examined alongside their expected revenue. Implementation should be supported by timely guidance, workable systems and realistic transition periods. Outcomes should then be reviewed against clear economic and operational criteria, with revision, postponement or withdrawal remaining genuine options when a measure underperforms.
None of this will end up on the front page of your favourite newspaper – and that is probably for the best.
But a stronger economy, productive investment, quality employment and Europe’s capacity to deliver on its strategic priorities certainly will. By embedding pro-growth principles throughout the tax policy lifecycle, the EU can ensure that its fiscal framework helps support those outcomes rather than quietly standing in their way.
Related items
Building trust without slowing innovation
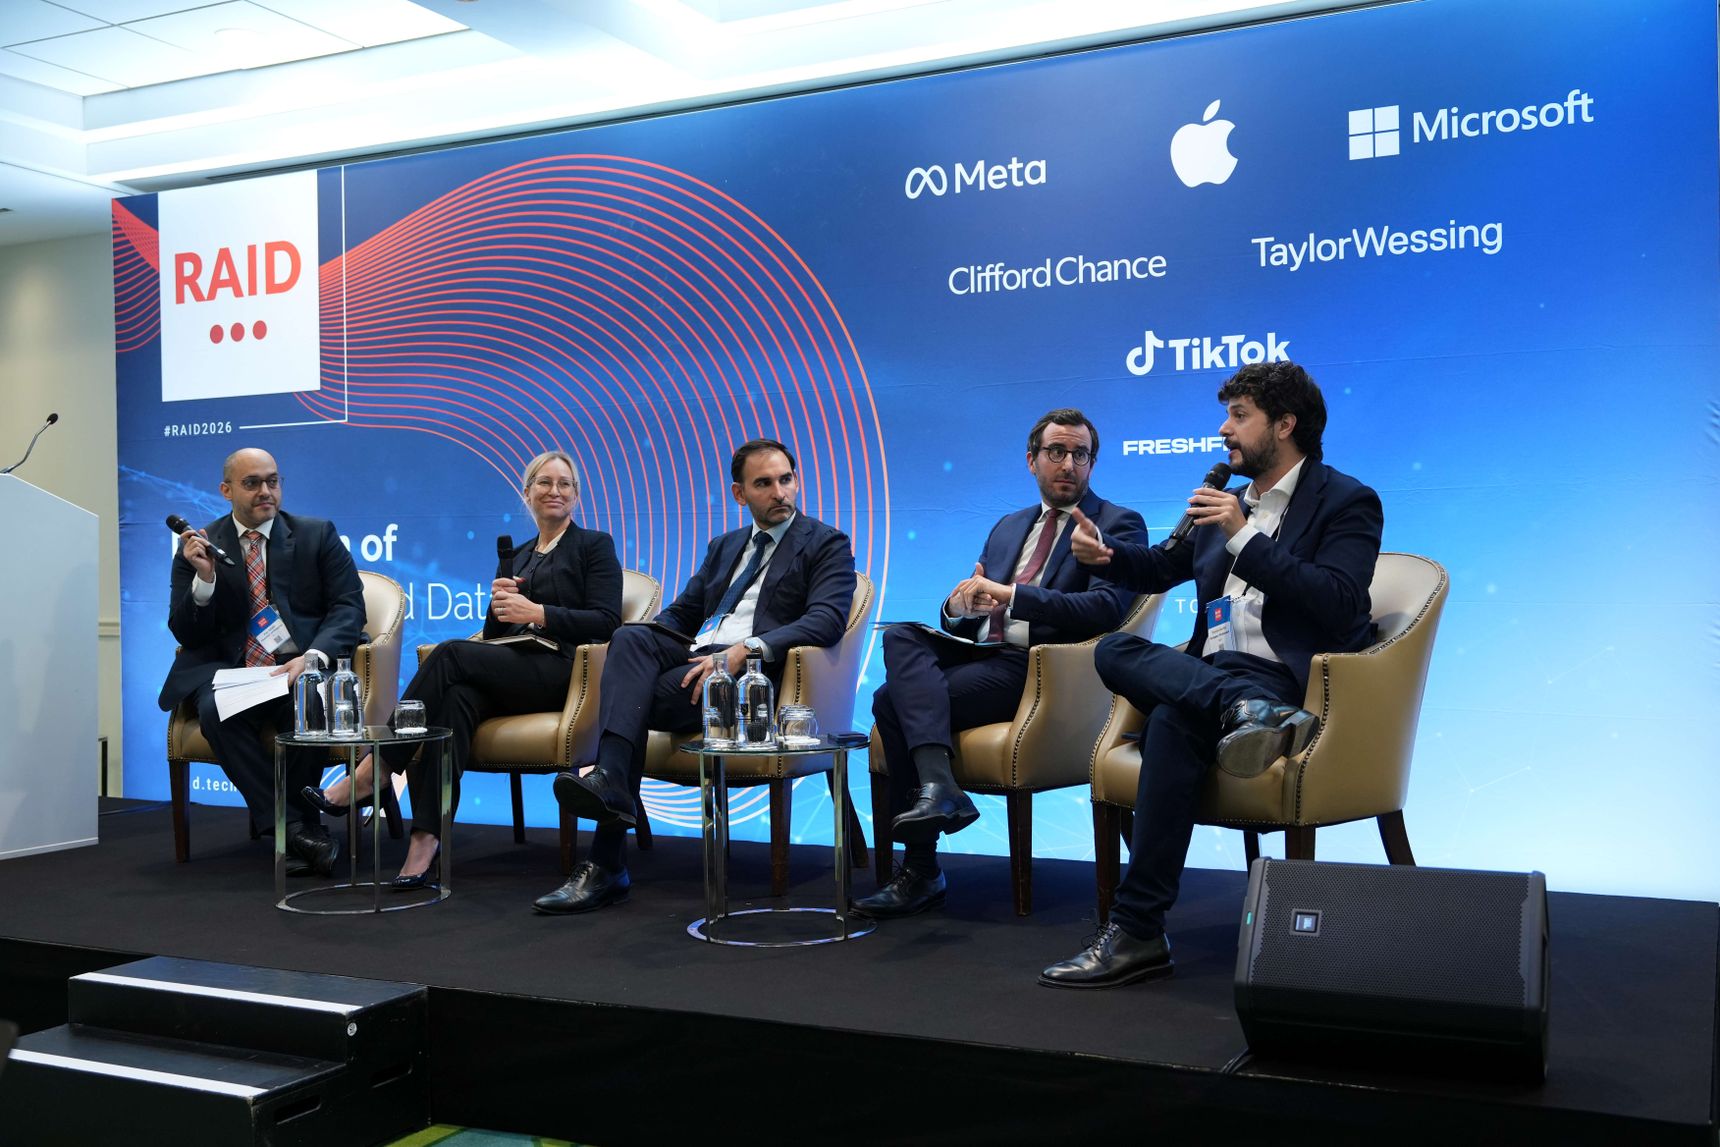
At RAID 2026, Thibaut L’Ortye, Chief Policy and Public Affairs Officer, AmCham EU joined a panel discussion on EU-US regulatory approaches to technology. Taking place on Tuesday, 29 September 2026, the discussion explored how transatlantic cooperation can focus on shared outcomes rather than identical rulebooks, including on cybersecurity, AI safety, consumer protection and resilient supply chains. Mr L’Ortye also highlighted the wider conditions needed to strengthen Europe’s competitiveness.

Closing the gap between customs and VAT rules
The reform of the Union Customs Code changes who is treated as the ‘importer’ when a non-EU company uses an indirect customs representative. That creates a problem under the EU VAT Directive, which links import VAT deduction to being identified as the importer or consignee. In practice, the non-EU company may no longer meet that requirement, while the customs representative may not qualify for the deduction either.
That could leave import VAT irrecoverable and create uncertainty for businesses using established import models. The Commission should ensure that the non-EU principal can still be identified in customs data for VAT purposes and fix the mismatch between the UCC and the VAT Directive.
Learn more about what changes are needed to keep import VAT deductibility workable under the new customs framework.

Gold-plating in practice
"Gold-plating" of EU legislation has become a structural challenge for companies operating across the Single Market. While Member States are often permitted to introduce additional national measures when implementing EU law, these divergences frequently create fragmented compliance requirements, administrative burdens and increased costs for businesses.
Drawing on examples from AmCham EU member companies across digital policy, cybersecurity, data protection, telecommunications, environmental regulation, consumer protection, tax transparency and labour law, the paper shows how national additions to EU rules can result in parallel compliance systems, duplicate reporting obligations, country-specific product adaptations and barriers to cross-border operations.
The paper highlights four key findings:
Divergence between Member States is often a bigger cost driver than any single regulatory requirement.
Fragmentation extends beyond directive transposition and also arises through opening clauses, national guidance, administrative practices and regional measures.
Minimum-harmonisation legislation can still create significant Single Market fragmentation.
Gold-plating occurs at both national and sub-national levels.
The European Commission should address these issues through greater consistency in implementation, increased transparency around national additions, reduced duplication in reporting and registration requirements, stronger implementation dialogue and the use of Single Market enforcement tools where appropriate. The objective is not to remove legitimate national discretion, but to prevent unnecessary regulatory barriers within the Single Market.
Policy priorities
Insights and advocacy driving Europe’s policy agenda. Our priorities support growth, innovation and a stronger transatlantic economy.
Membership
Connecting business and policymakers to strengthen the voice of American companies in Europe.