Technology and software transfers in the context of export controls
Related items
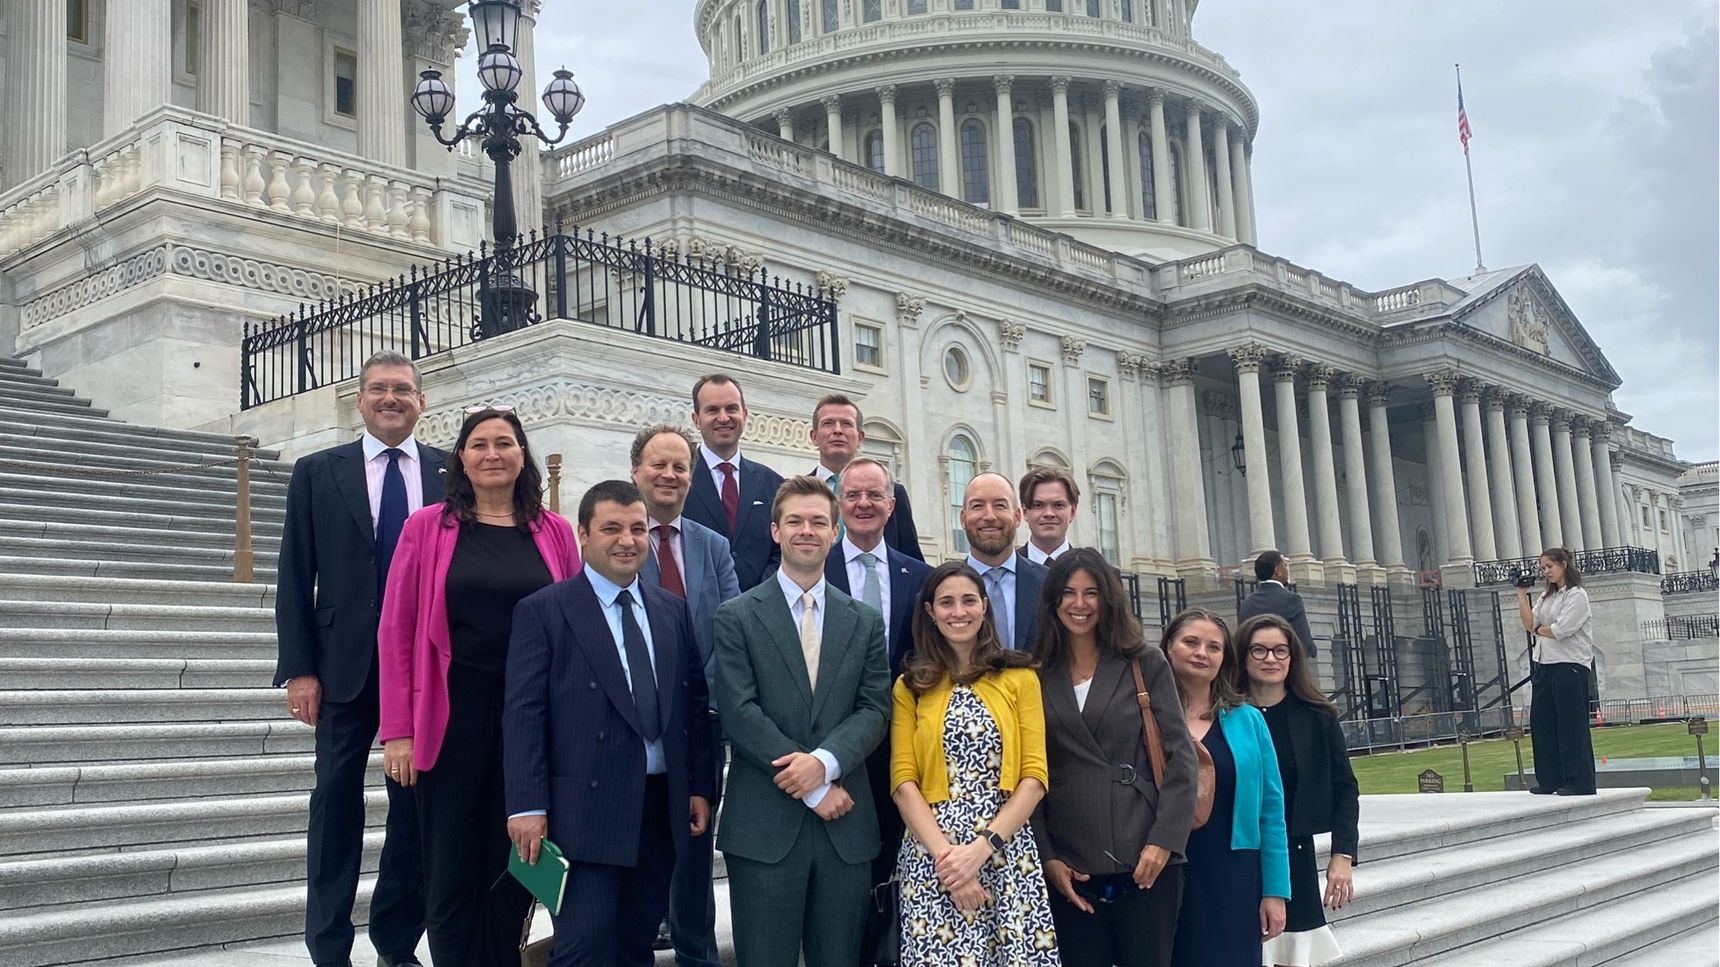
Making the case for the transatlantic relationship in Washington, DC
From Monday, 28 September to Thursday, 1 October 2026, AmCham EU led a delegation of members to Washington, DC to bring the views of the business community to policymakers in Congress and the administration. Discussions showed that both sides value the stability the Turnberry framework agreement brings. While parts of the agreement remain to be implemented, meetings pointed to the possibility for cooperation on economic security. Implementation will continue to need dialogue between the two sides, which is expected to carry on after the mid-term elections.
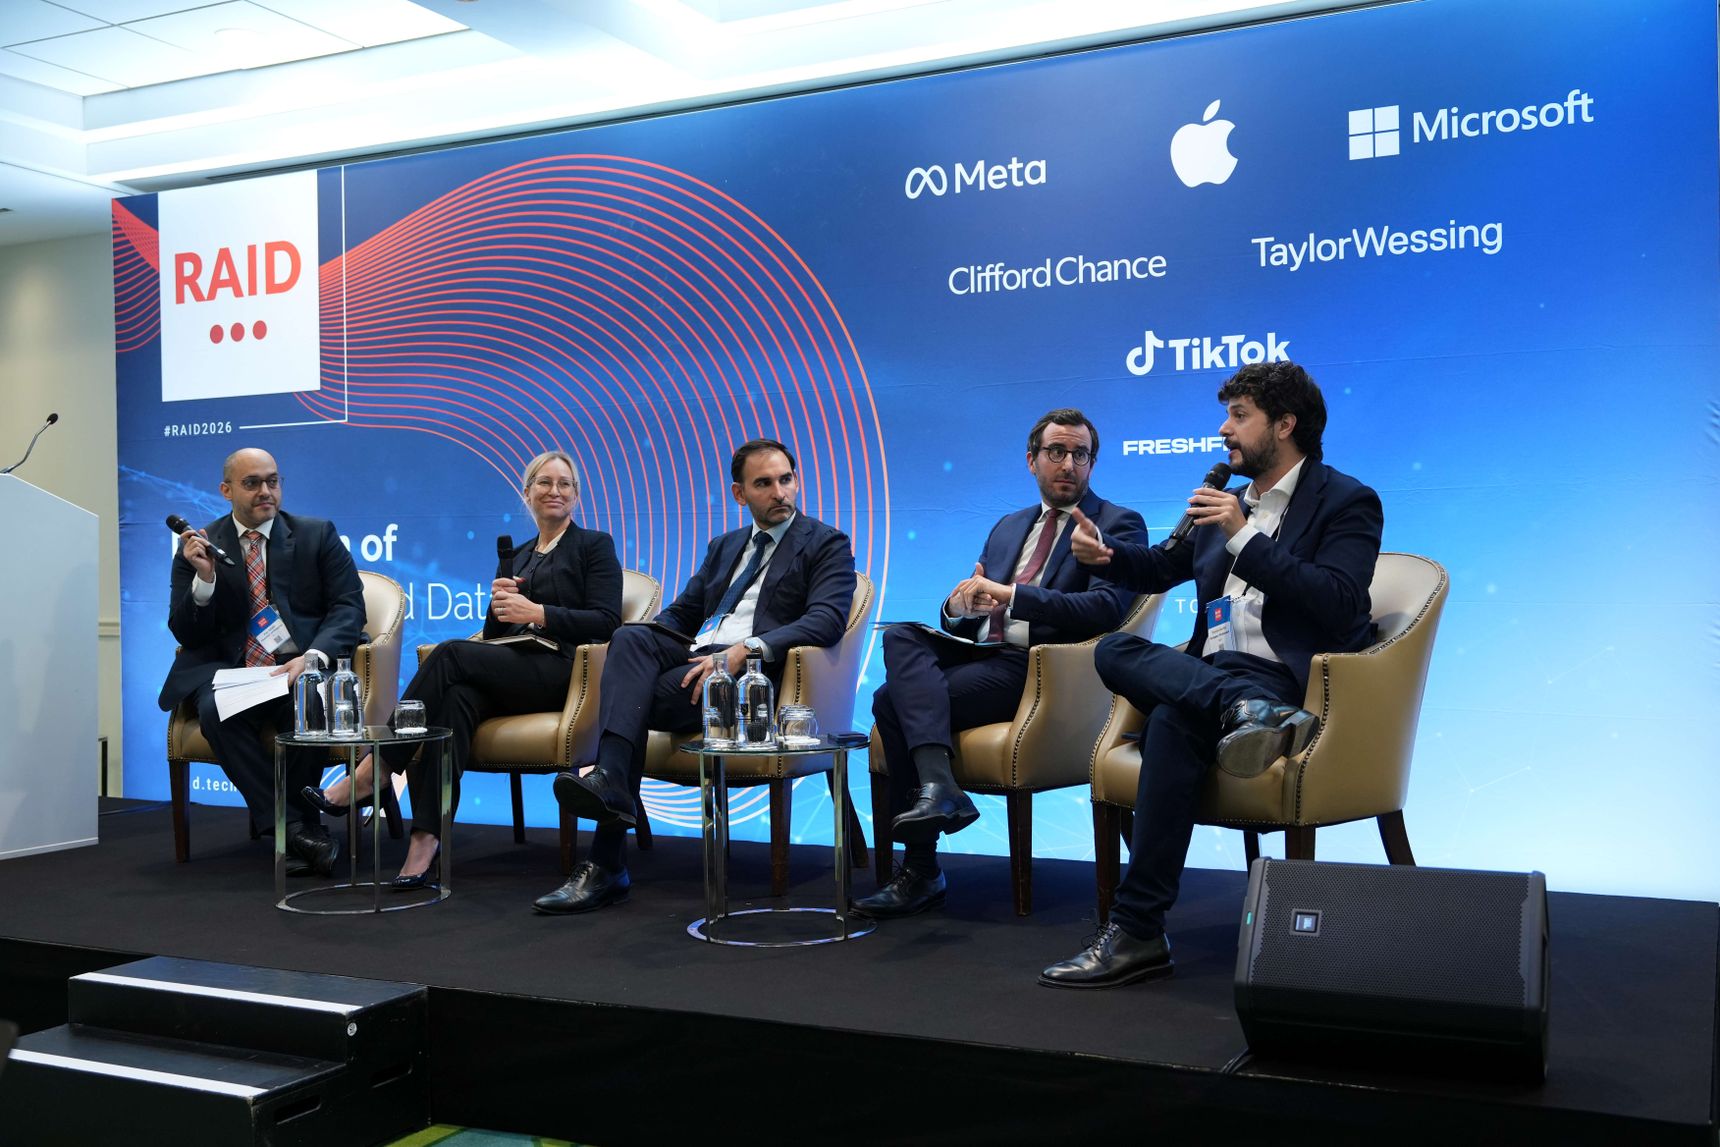
Building trust without slowing innovation
At RAID 2026, Thibaut L’Ortye, Chief Policy and Public Affairs Officer, AmCham EU joined a panel discussion on EU-US regulatory approaches to technology. Taking place on Tuesday, 29 September 2026, the discussion explored how transatlantic cooperation can focus on shared outcomes rather than identical rulebooks, including on cybersecurity, AI safety, consumer protection and resilient supply chains. Mr L’Ortye also highlighted the wider conditions needed to strengthen Europe’s competitiveness.

Closing the gap between customs and VAT rules
The reform of the Union Customs Code changes who is treated as the ‘importer’ when a non-EU company uses an indirect customs representative. That creates a problem under the EU VAT Directive, which links import VAT deduction to being identified as the importer or consignee. In practice, the non-EU company may no longer meet that requirement, while the customs representative may not qualify for the deduction either.
That could leave import VAT irrecoverable and create uncertainty for businesses using established import models. The Commission should ensure that the non-EU principal can still be identified in customs data for VAT purposes and fix the mismatch between the UCC and the VAT Directive.
Learn more about what changes are needed to keep import VAT deductibility workable under the new customs framework.
Policy priorities
Insights and advocacy driving Europe’s policy agenda. Our priorities support growth, innovation and a stronger transatlantic economy.
Membership
Connecting business and policymakers to strengthen the voice of American companies in Europe.